
The Solution Bridge Blog
Can a reviewer trace this receipt to the ledger?
Build a two-way reference between a source document and its ledger entry without relying on a filename alone.
Applies to: U.S. business bookkeeping; evidence organization, not a tax-deductibility decision.
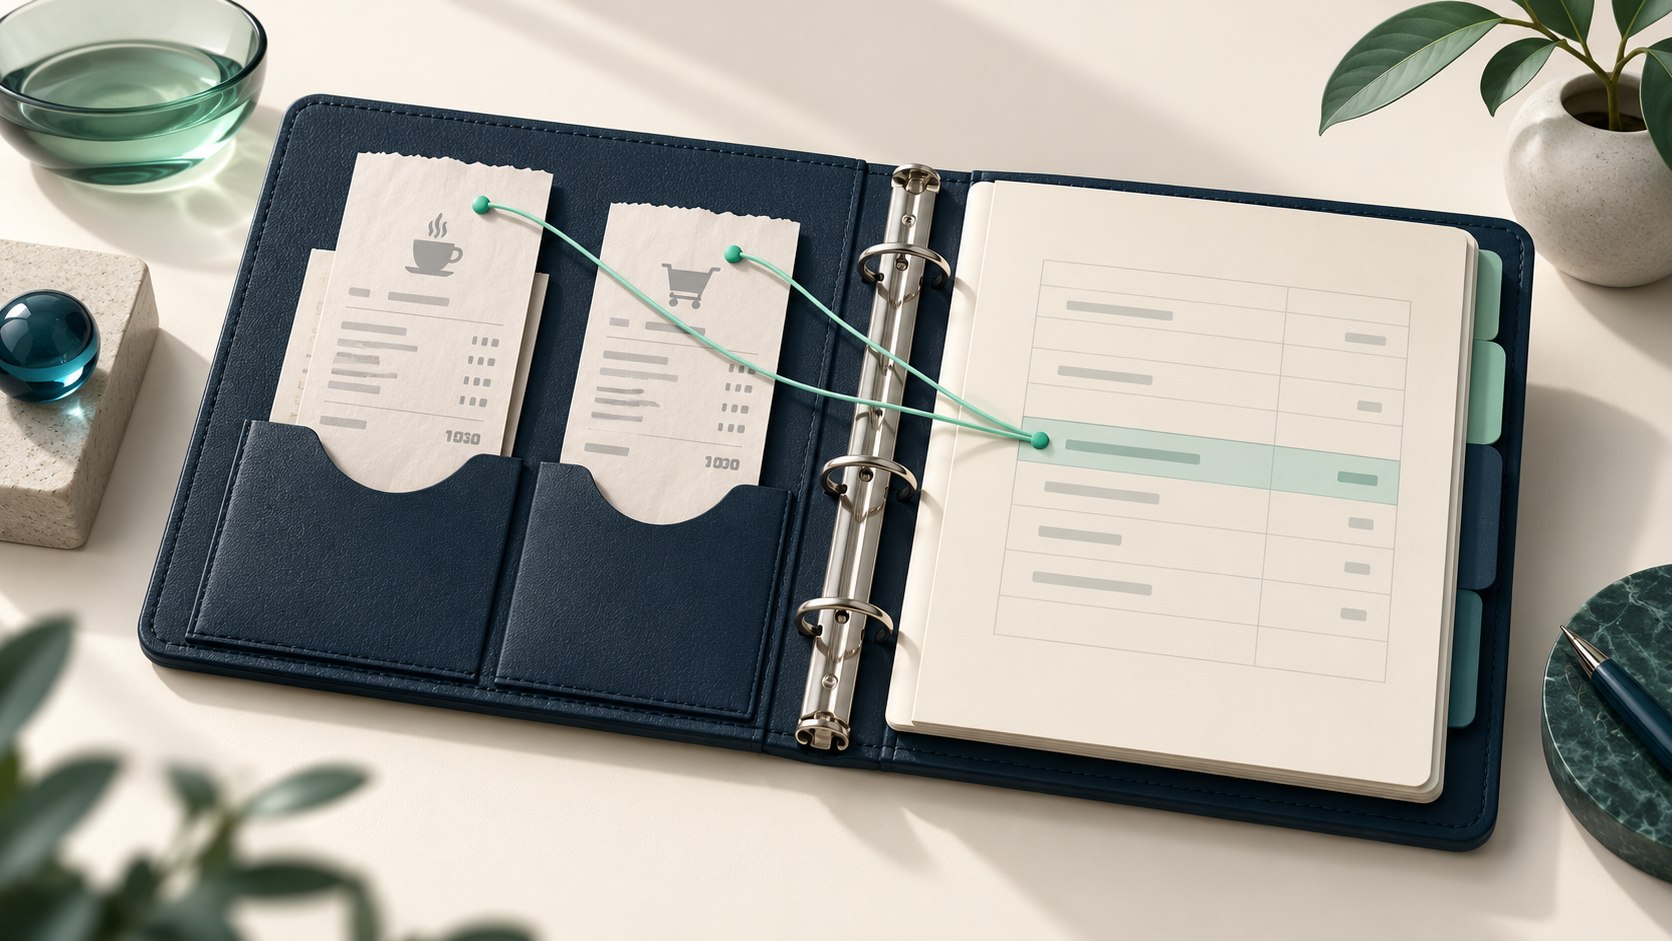
A folder full of receipts can still leave a reviewer unable to explain an expense. The missing piece is often the connection between the document and the entry, especially when several purchases have the same amount. Build a reference that works in both directions: from entry to evidence and from evidence back to the entry.
IRS Publication 583 explains the importance of supporting records, including documents behind purchases and other transactions. A payment record by itself may not explain the business purpose. IRS Publication 583.
A focused review checklist
- Give the transaction a stable internal reference; keep the original supplier document number too.
- Record supplier, document date, amount, currency and the ledger entry reference together.
- Check whether a payment receipt and an invoice describe the same purchase before treating them as separate costs.
- Record what remains missing and the person responsible for obtaining it.
- Test the reference by asking a reviewer to locate the source without a verbal explanation.
A hypothetical example
A hypothetical team has three $85 charges on one date. Naming each file receipt-85 does not distinguish them. A stable reference paired with supplier and account information helps identify which charge relates to which receipt. If the purpose remains unclear, keep it as an open review question rather than inventing a description.
Keep the source document intact when adding an index or annotation. If a file is replaced with a clearer copy, retain enough version information to explain the change. The goal is a useful evidence trail, not a complicated naming system that only one employee understands.
For help organizing the records and open questions, see our bookkeeping and accounting service. Share sensitive records only through an agreed secure channel.
Questions about this review
Does a filename prove the expense is valid?
No. It helps find evidence; the underlying transaction and its treatment still need review.
What if the supplier number repeats?
Pair it with supplier identity and a stable internal reference rather than assuming global uniqueness.
Should a missing receipt be silently replaced with a bank statement?
No. Identify the evidence available and what it does not explain, then ask the reviewer for the appropriate next step.
Prepared by The Solution Bridge. Sources checked October 22, 2026. Educational guidance; verify current product instructions and applicable requirements.
Useful answers
Bookkeeping FAQs
What should I prepare before a bookkeeping review?
Start with the period, bank and card statements, sales and purchase records, and a list of unresolved transactions. Agree a secure document-sharing method before sending files.
Should I guess a category for an unclear transaction?
Keep it on an exception list with its date, amount and question. Ask the responsible person for supporting evidence before approving the final treatment.
Can bookkeeping support include catch-up work?
Catch-up work can be discussed separately. The period, missing documents, software access and review responsibilities determine the scope.
Talk to The Solution Bridge
Let’s make your next step clearer
Tell us what you need help with. For software enquiries, include the product, version and exact message. Please leave out passwords, tax identifiers and financial documents.